

In February 2022, Russia discovered that a foreign-exchange reserve is only as sovereign as the system holding it.
For years, Moscow had accumulated hundreds of billions of dollars in reserves, partly as protection against financial pressure from the West. When Russian forces entered Ukraine, the United States and its allies froze a large portion of those assets.
For central banks elsewhere, the freezing of those reserves established a precedent that extended beyond Russia. A country could spend decades earning foreign currency, running trade surpluses and accumulating reserves, only to discover during a geopolitical confrontation that access to part of those savings depended upon decisions made in Washington, Brussels and other Western capitals.
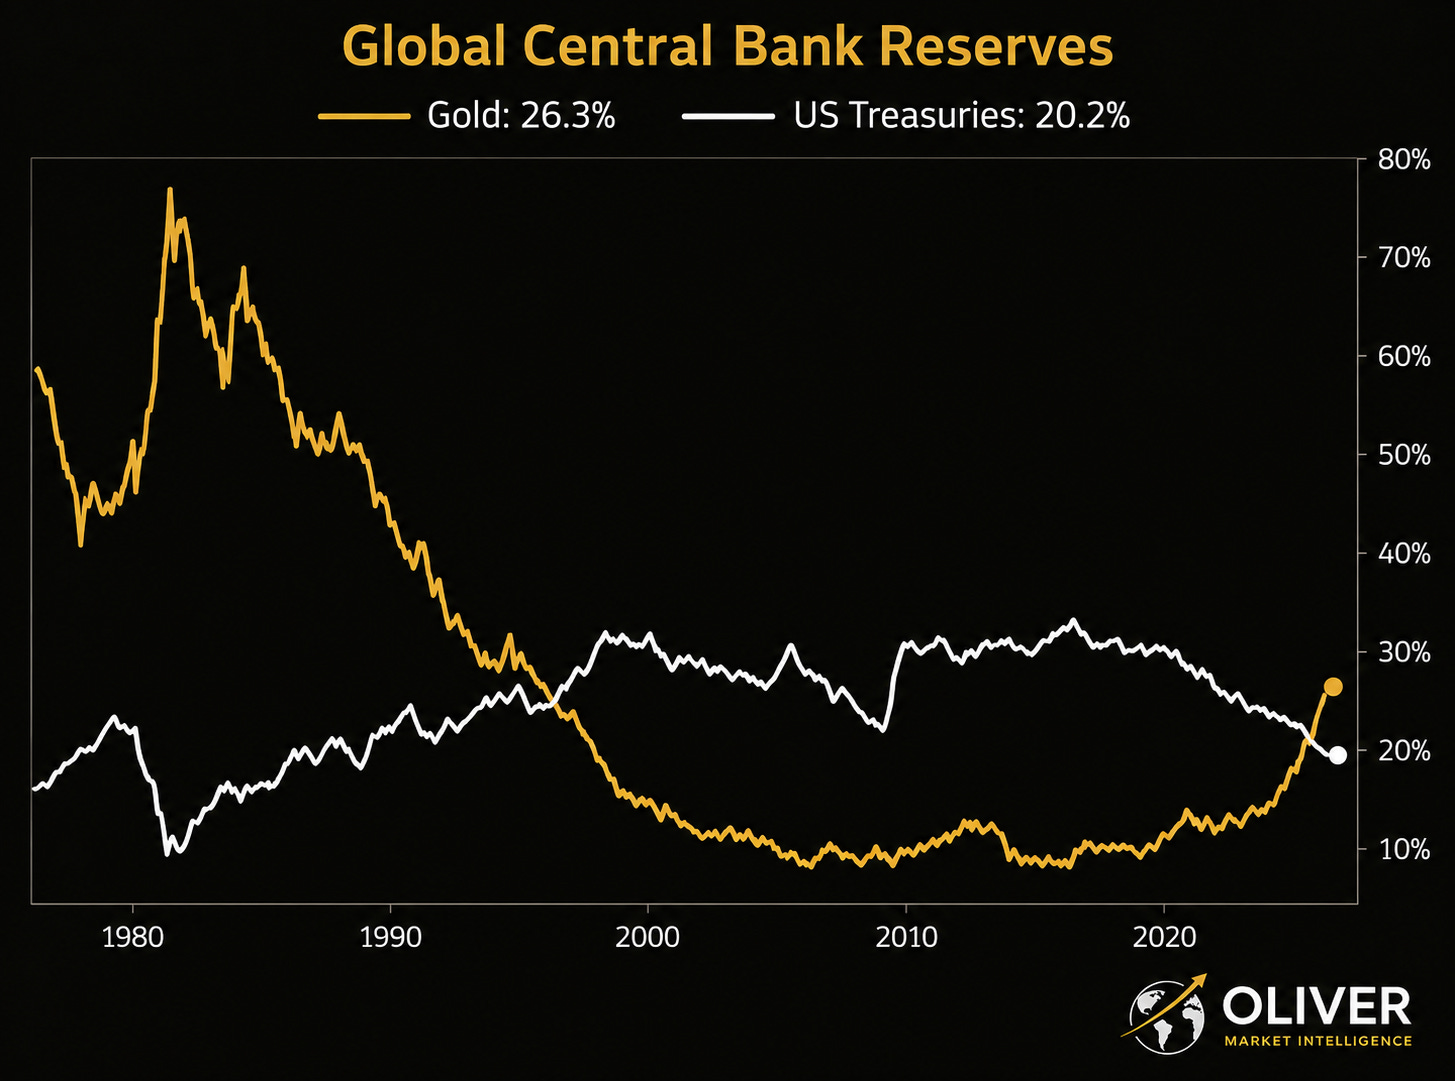
For China, Saudi Arabia and other large reserve holders, the episode made the political conditions attached to foreign reserves considerably harder to ignore. Central banks continued accumulating gold while governments experimented with local-currency trade and payment systems requiring less Western financial infrastructure.
Freezing Russia’s reserves demonstrated the reach of American financial power while giving other governments a reason to reduce their exposure to it.
Four years later, Washington is applying the same financial leverage more aggressively against Iran. Scott Bessent is threatening to exclude institutions financing Tehran from the dollar system while America fights a Middle Eastern war, searches for petroleum in Venezuela and watches Japanese bond yields climb towards levels unseen for decades. At home, strategic reserves are being consumed while Treasury yields remain stubbornly high.
There is nothing unusual about finding a separate explanation for each event. The pattern becomes harder to dismiss when they begin occurring at the same time.
Over the past few weeks, we have followed several of these pressures separately. What is becoming clearer is how quickly they are beginning to collide.
This is what de-dollarisation looks like in motion.
When the Dollar Becomes a Weapon
The dollar’s extraordinary power comes partly from the difficulty of avoiding it.
Global banks require access to dollar clearing. Commodity trade remains heavily dollarised. Governments hold Treasuries as reserves. Companies borrow in dollars. Financial institutions operating thousands of miles from New York still depend upon American financial infrastructure.
Washington has spent decades learning how to turn that dependence into leverage.
Bessent has now taken the idea unusually far. Under what Treasury calls Operation Economic Outcast, the United States is attempting to sever Iran’s financial connections across the world. Bessent’s warning could hardly be clearer: entities facilitating Iranian financial activity risk removal from the US dollar system. Treasury is targeting petroleum networks, shipping, aviation, technology, digital assets and even gold.
If America possesses the world’s dominant financial network, denying an adversary access to it is enormously powerful.
The problem appears further down the road.
Every demonstration of that power gives governments another reason to reduce their dependence upon it.
China has already absorbed that lesson. banks facilitating sanctioned trade could find themselves confronting a choice between business with Iran and access to the dollar system. Even countries with little affection for Tehran can understand the precedent. Reserves held inside another country’s financial architecture are reserves held partly at that country’s discretion.
De-dollarisation does not require governments to dislike America. Self-preservation is enough.
As we argued recently in The Dollar’s Long Goodbye, the dollar does not need to collapse for this to matter. It only requires governments to become slightly less willing to hold their reserves inside somebody else’s financial system.
The Cost of Fighting on Every Front
But financial pressure is only one constraint Washington now faces.
The Iran war has already placed extraordinary pressure on American strategic resources. The Strait of Hormuz sits at the centre of the confrontation, threatening one of the most consequential petroleum arteries on earth. America’s Strategic Petroleum Reserve, designed precisely for severe disruptions to energy supply, has meanwhile fallen to roughly 286 million barrels after enormous withdrawals during the first months of the war, according to the material supplied for this article.
That helps explain the significance of Trump's Venezuelan oil agreement.
Washington has announced majority control over 17 Venezuelan oilfields containing more than 65 billion barrels of proven reserves. The 65 billion-barrel figure is enormous, although much of its immediate political usefulness disappears once the practical details are considered.
The United States possesses enormous military and financial power, yet finds itself searching abroad for resources while its own strategic buffers become thinner.
Reserve-currency systems have never rested on finance alone. They rest upon confidence that the country issuing the reserve asset possesses the economic, political and military capacity to defend the system surrounding it.
The more expensive those commitments become, the more heavily they eventually bear on the currency supporting them.
When Japanese Money Comes Home
Then there is Japan.
For decades, Japan provided one of the quiet subsidies beneath American financial dominance.
Japanese interest rates were crushed towards zero. The Bank of Japan accumulated enormous quantities of government bonds. Japanese institutions looked overseas for returns, while global traders borrowed cheaply in yen and deployed that capital into higher-yielding assets elsewhere.
America benefited enormously.
Japan remains the largest foreign holder of US government debt, with more than $1 trillion in Treasuries. But Japanese government bond yields are now climbing towards levels unseen for decades. The 10-year JGB has approached 3 per cent, while the 30-year has moved above 4 per cent.
A 3 per cent domestic yield gives Japanese capital far less reason to leave home.
A Japanese insurer no longer faces the same choice between earning almost nothing domestically and reaching abroad for American yield. Higher JGB yields make repatriating capital increasingly defensible, particularly after accounting for currency hedging costs. Japan does not need to dump Treasuries for this to matter. Marginal buyers simply need to become less enthusiastic.
We covered the mechanics of this reversal in more detail last week in Japan and the End of Easy Money. The point worth carrying forward is simpler: one of America’s most dependable creditors suddenly has more reason to keep its money at home.
Bessent Meets the Market
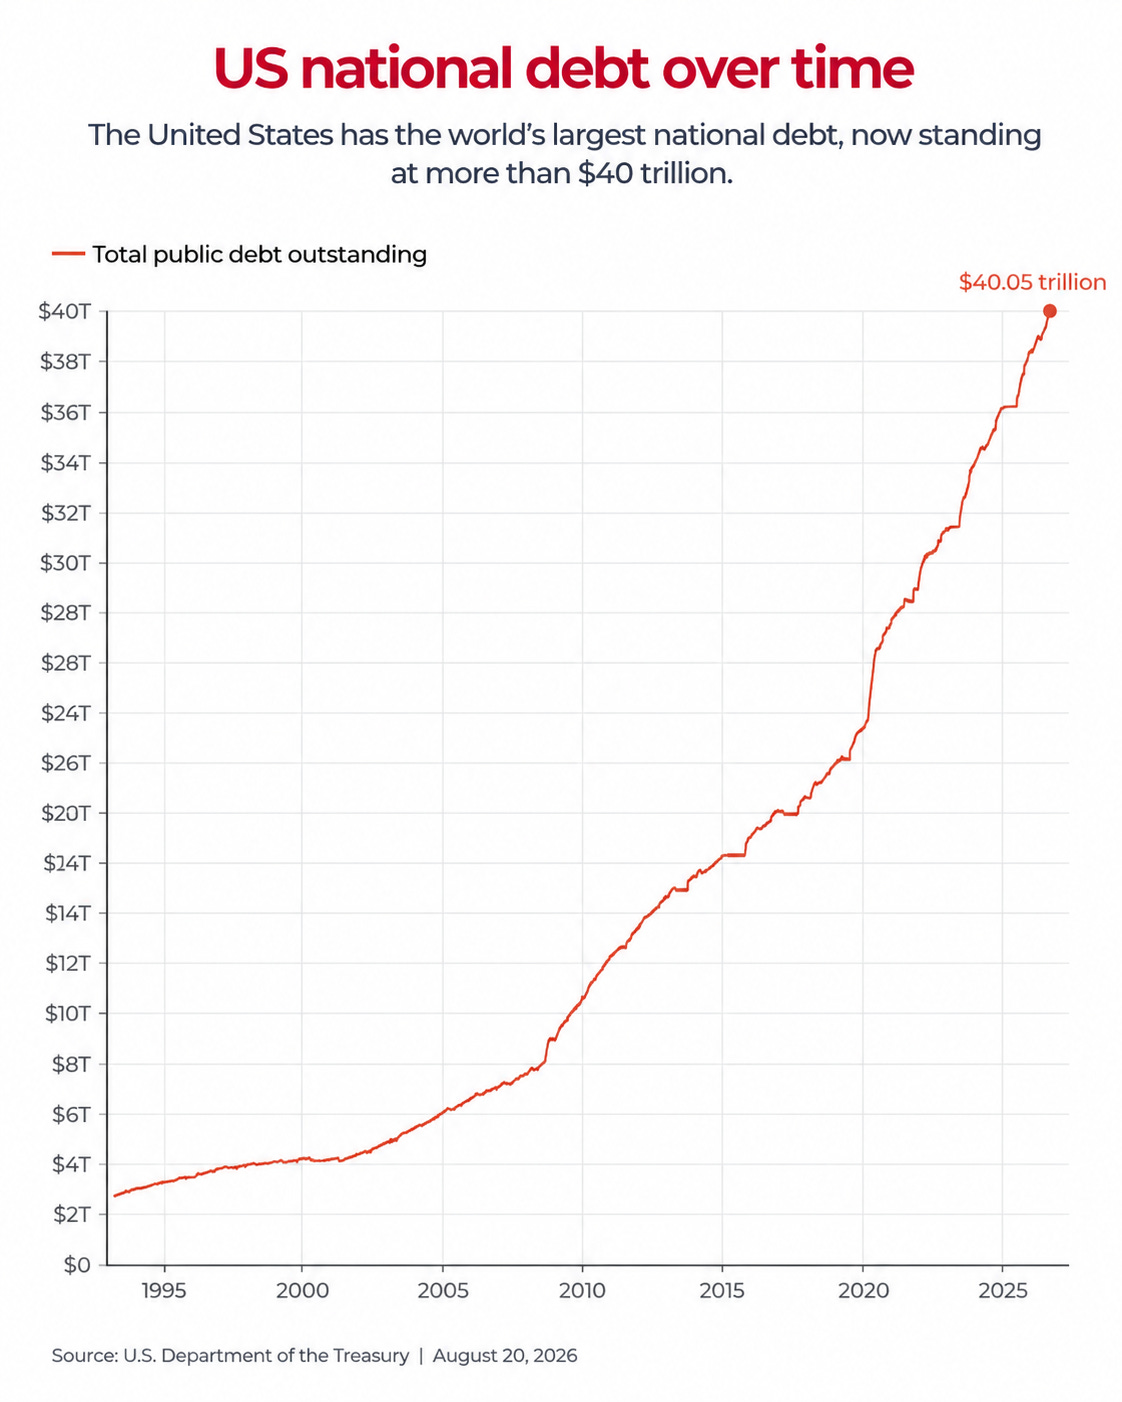
US federal debt has passed $40 trillion. Interest expense is around $1.2 trillion annually. Long-term Treasury yields have climbed towards levels last experienced before the financial crisis.
Bessent is trying to push against that pressure.
Treasury has expanded bond buybacks, purchasing longer-duration securities while considering greater reliance upon short-term bills. Buying long bonds supports their prices and, mechanically, pushes their yields lower.
For a moment, it worked.
Then yields began climbing again.
America is using access to its currency as an instrument of foreign policy while simultaneously requiring foreigners to purchase unprecedented quantities of its debt. It is threatening governments and financial institutions with exclusion from the dollar network while depending upon that same network to recycle global savings into Treasuries.
Japan, historically one of America’s most dependable creditors, suddenly has more reason to keep capital at home.
China has obvious strategic reasons to reduce its exposure.
Oil-producing governments have watched dollar reserves become geopolitical instruments.
Countries trading with sanctioned states are being reminded that participation in the dollar system comes with conditions.
Meanwhile, Washington keeps issuing bonds.
The Bond Market Gets the Final Vote
The long end of the Treasury curve says more about this transition than another speech about the dollar's reserve status.
Bond investors do not need to predict the collapse of American power. They simply need to demand greater compensation for holding American promises for thirty years.
Recent pricing suggests that compensation is already rising.
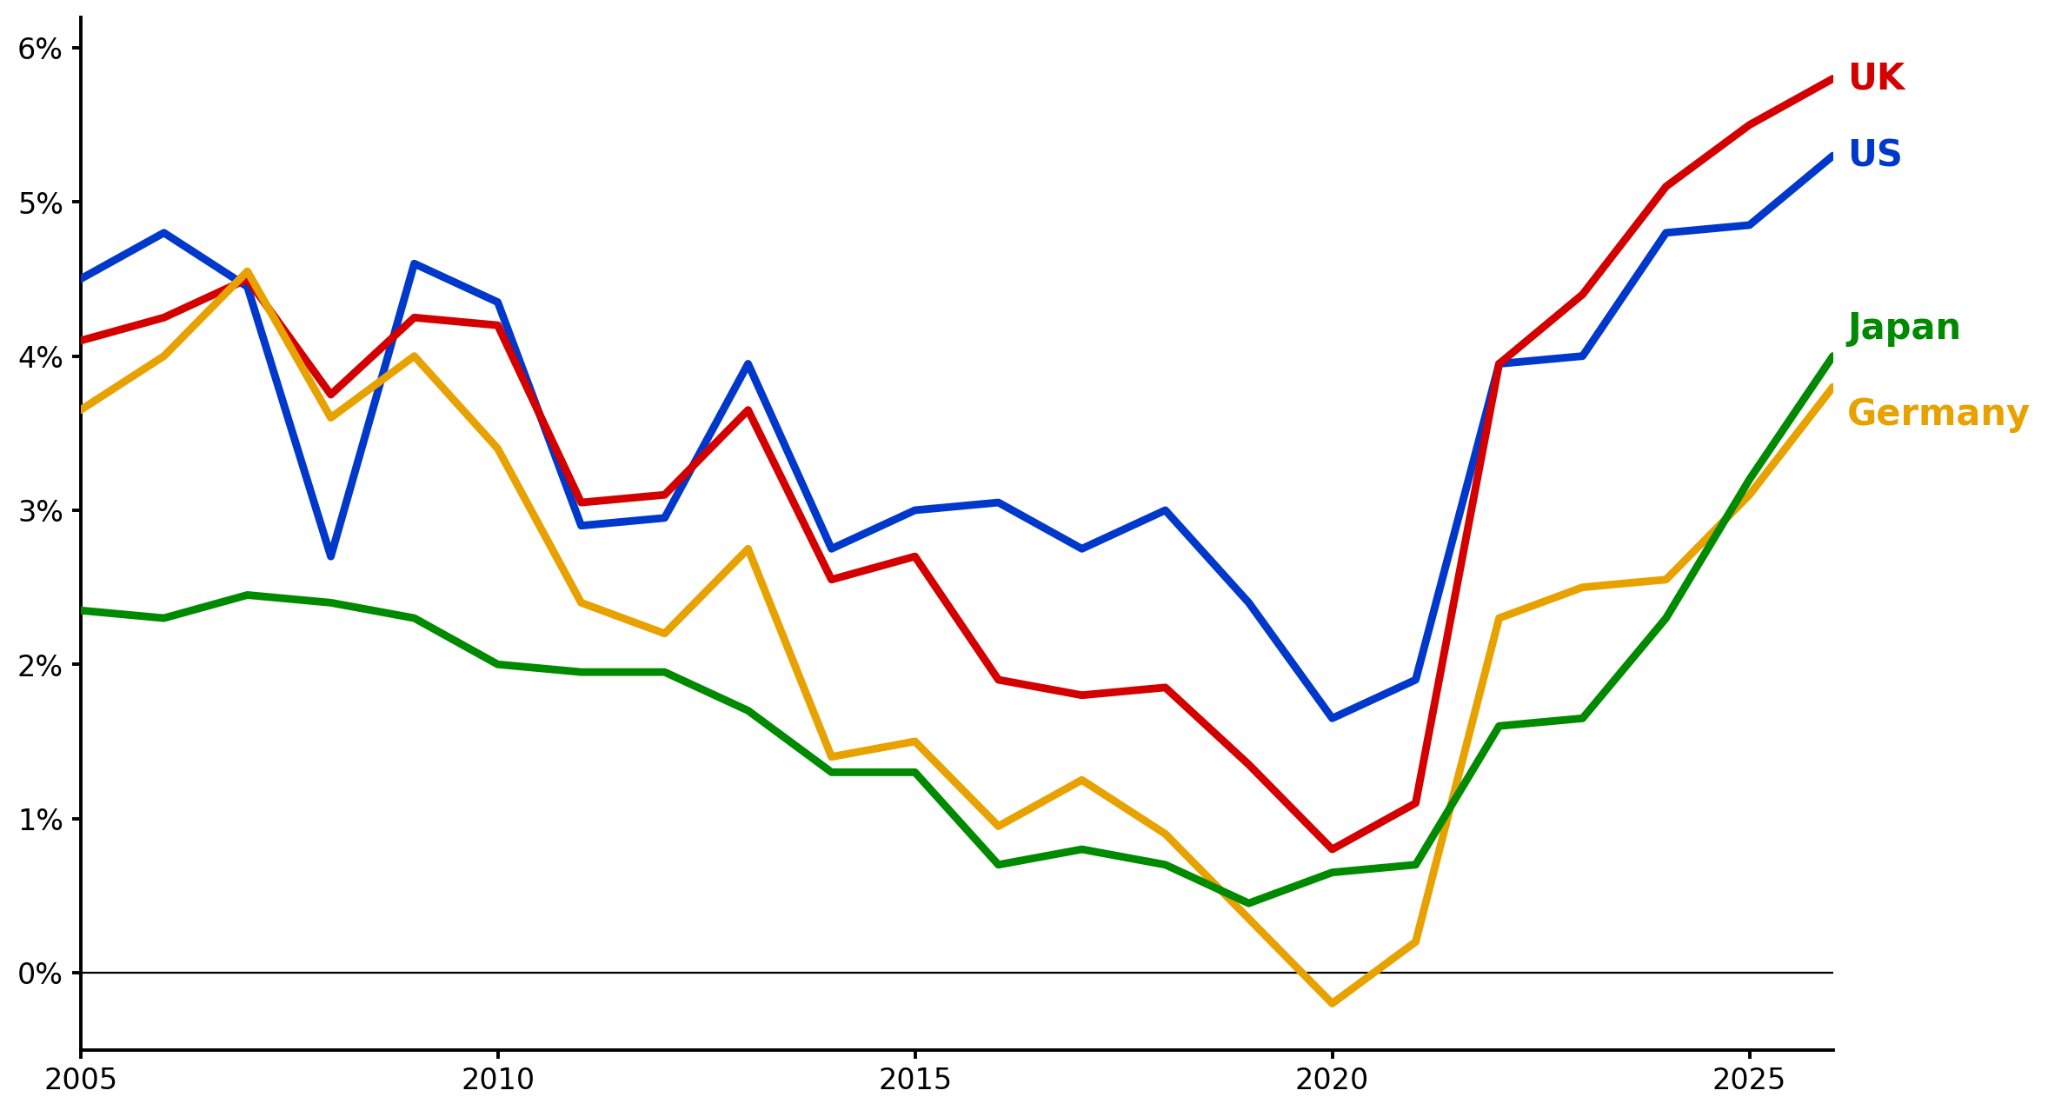
Thirty-year Treasury yields recently reached around 5.3 per cent. British long bonds are approaching 6 per cent. Japanese yields are reaching levels unseen since the 1990s. Across developed markets, investors are demanding more compensation for duration, inflation, fiscal uncertainty and relentless sovereign issuance.
Bessent can conduct buybacks. Treasury can alter issuance. The Federal Reserve can change short-term rates. Washington can sanction banks, seize financial assets and threaten exclusion from dollar clearing.
It cannot order somebody to lend the United States money for thirty years at 4 per cent.
That price belongs to the market.
Gold Has No Counterparty
Normally, rising bond yields should hurt gold.
A metal paying no interest ought to struggle when supposedly risk-free government debt offers 5 per cent. Yet gold has remained remarkably resilient while sovereign yields climb.
A 5 per cent Treasury yield means one thing when investors are being generously compensated for holding an unquestionably safe asset. It means something different when lenders are demanding greater compensation for inflation, fiscal deterioration, political intervention and uncertainty over the future purchasing power of the currency in which they will be repaid.
Gold sits outside that negotiation.
It has no finance ministry behind it. No central bank must defend it. Nobody can exclude another country from the gold system because no such system exists. It carries no counterparty promise and cannot be created to finance a budget deficit.
For reserve managers trying to reduce political dependence on another sovereign, those characteristics have acquired new value.
Russia discovered this in 2022. Hundreds of billions of dollars in foreign reserves provided considerable financial protection until geopolitics determined that much of it could no longer be accessed. The reserves still existed on paper. Moscow’s ability to use them did not.
Washington today possesses extraordinary financial power precisely because so much of the world still operates through dollars. The dollar remains dominant, Treasury markets remain enormous and predictions of its imminent death deserve scepticism. But every use of that power gives foreign governments another reason to consider how much exposure they are willing to maintain.
Bessent faces a harder problem in the bond market.
The bond market does not care about speeches. It does not salute the flag. It simply keeps asking what price is required to hold another thirty years of promises.
For now, investors keep demanding more.
And while Washington searches for ways to push that price back down, central banks have quietly been accumulating the one reserve asset that cannot be frozen by another government, excluded from a payment network or created to finance another trillion-dollar deficit.
Gold.
If you are thinking about how to protect your wealth in this environment, you can explore physical gold and silver through www.goldwise.com, where the focus is on ownership, security and transparency.
Goldwise is committed to producing educational content that helps investors better understand the macroeconomic forces shaping financial markets. If there are topics you would like us to explore in future editions, we welcome your feedback.
Disclosure: Mr. Matthew Oliver, Oliver Market Intelligence, is a Goldwise shareholder. Any opinions, analysis and views expressed in this publication are solely those of Mr. Matthew Oliver, Oliver Market Intelligence and are provided independently unless expressly stated otherwise.
This publication is provided for informational and educational purposes only and does not constitute financial, investment or other professional advice. References to Goldwise are for informational purposes and should not be construed as a recommendation to purchase any product or service. Investments can fall as well as rise in value, and readers should conduct their own research and, where appropriate, seek advice from a qualified financial adviser before making any financial decisions.
The most interesting tension here is that the dollar’s reach makes financial sanctions powerful, while each use of that power may strengthen the case for diversifying reserves. I’d be careful, though, about treating higher long-term Treasury yields as a direct measure of de-dollarisation. Inflation expectations, fiscal supply and the compensation investors demand for holding long bonds can move yields too. The question I’d keep watching is whether reserve managers actually change what they hold over time. That would tell us more than a single move in the bond market.